Private Equity in Renewable Energy: How it Works


No time to read? Let AI give you a quick summary of this article.


Investing in renewable energy has grown from a new trend into a core strategy for many funds. Global warming and the long-term plans of leading governments to cut carbon emissions by 2050 are the main drivers.
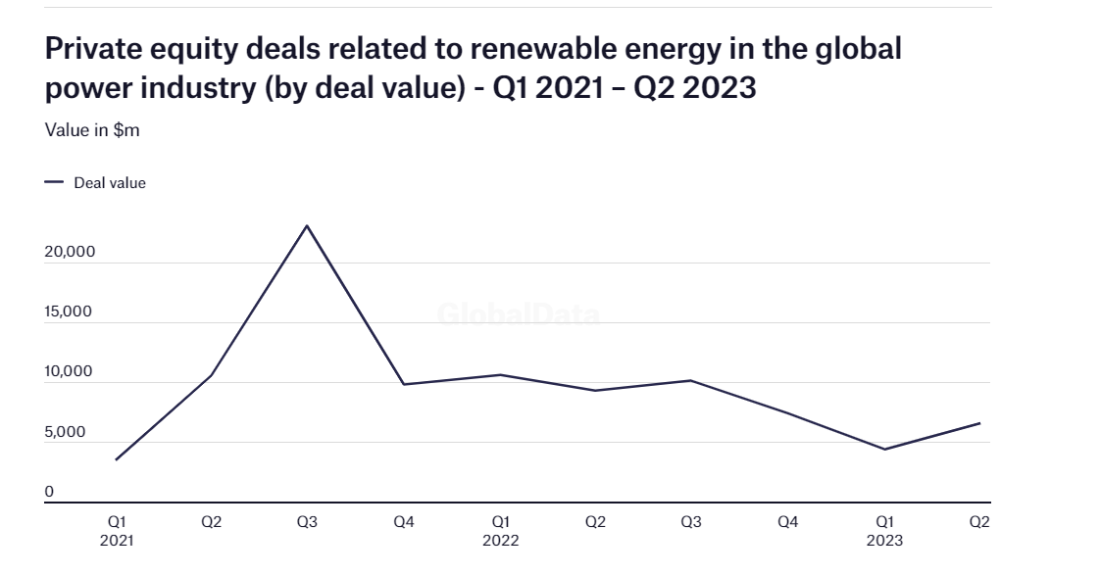
Private equity deal activity in renewables surged in 20221, peaked in Q4 2022 and cooled through 2023. The wider market has since reached new highs. BloombergNEF reported on 26 January 2026 that global energy transition investment hit a record $2.3 trillion in 20252, up 8% on 2024. Electrified transport led at $893bn (up 21%), followed by renewable energy at $690bn and grids at $483bn.
The headline total hides one dip. Renewable energy investment itself fell 9.5% year on year in 2025, mainly because changes to China’s power market rules created uncertainty. US transition investment still rose 3.5% to $378bn despite policy headwinds, and energy transition debt issuance grew 17% to $1.2tn. BNEF’s base case expects average annual investment of $2.9tn over the next five years.
What drives the fluctuations of the interest in renewable energy investments? Can this interest be sustained in the long run?
At first glance, there are no reasons for such a drop, because the advancements in the renewable energy sector seem promising:
- Utility-scale solar PV has become much cheaper. IRENA’s Renewable Power Generation Costs in 20243 report puts the global weighted average cost of electricity (LCOE) at $0.043/kWh in 2024. That is down about 90% from $0.417/kWh in 20104. Installed costs fell 87% over the same period, to $691/kW.
- Onshore wind’s LCOE has fallen 70% since 20105, to $0.034/kWh in 2024. That makes it the cheapest source of new power.
- Battery storage costs fell 93% between 2010 and 2024, to $192/kWh. Renewable energy can now be stored for longer and at a lower cost.
Finally, government support and the EU’s zero-emission strategy6 for 2050 should keep private equity investors interested in renewable energy. This holds even though US federal policy has become less generous.
So why does capital flow unevenly across technologies and markets, and how does that affect private equity investments in the renewable energy sector?
What you will learn in this post:
Challenges and risks for renewable energy investors
The data does not show investors walking away. The IEA’s World Energy Investment 2025 report7 (June 2025) expected global energy investment to reach a record $3.3tn in 2025, up 2% in real terms. About $2.2tn of that was going to renewables, nuclear, grids, storage, low-emissions fuels, efficiency and electrification. That is twice the roughly $1.1tn going to oil, gas and coal. Solar was the largest single category, at about $450bn.
In 2022, private equity companies came under more pressure to decarbonize their portfolios, and fund managers turned to renewable energy projects. The race to develop new renewable sources pushed investment volumes up further. For a while, renewable energy looked like the next gold mine for anyone with capital to put to work.
Additionally, renewable energy investments create new jobs, contribute to economic growth, and increase energy independence.
While all the mentioned reasons are valid, we shall not forget that the main aim of any private equity investment firm is profit.
So what returns can investors expect today? Private capital remains committed. CBRE Investment Management reports that private infrastructure fundraising passed $175bn in Q1–Q3 20258, a new high. Renewables took about two-thirds of sector-specific fund allocations, and data centres took close to 20%. The risks have not disappeared, but they have become more specific:
- Financing costs. Higher interest rates raise the cost of capital for projects that need heavy upfront spending and then depend on decades of steady cash flow.
- US policy. The 2025 tax law cut short federal credits for new wind and solar projects (see the incentives below).
- Offshore wind. Supply-chain disruption has hurt returns. Offshore wind LCOE rose 4% in 2024, and installed costs reached $2,852/kW. Onshore wind LCOE rose 3%.
- Critical minerals. The transition needs far more mined materials, which exposes projects to price and supply risk.
To shift to a zero-carbon emission world, we would need a lot of natural resources, and these resources must be extracted from the earth. The commonly cited list includes lithium, cobalt, manganese, copper, silicon, and other rare materials. In fact, it mixes scarce minerals with abundant ones such as copper and silicon. Demand growth is also smaller than often claimed. In its Global Critical Minerals Outlook 20269, the IEA projects that overall critical-mineral demand will almost double by 2040 under stated policies:
- Lithium shows the strongest growth, more than threefold.
- Nickel, graphite and rare earths grow by about 50–90%.
- Copper demand rises by 25% or more, adding about 7 million tonnes.
For investors, supply is the real constraint. The IEA estimates that more than $750bn of mining and refining investment is needed to 2040. Persistent gaps in copper and lithium supply can raise equipment costs and delay projects.
Now let’s look at the economics of individual wind and solar projects.
A wind turbine is a capital-intensive asset10, with a large upfront cost and yearly maintenance. However, comparing one turbine’s output with a whole coal plant’s output says nothing about which investment pays better. The useful measure is the cost per unit of electricity. On that basis, new onshore wind was the cheapest source of new power in 2024, at $0.034/kWh and 53% cheaper than the cheapest fossil fuel alternative11.
Now, let’s have a look at solar energy. The time a solar installation takes to pay back depends heavily on the market12: incentives, energy prices, tax credits and financing all move it. For example, US homeowners lost the federal residential solar credit after 2025, which lengthens payback for home systems.
Solar panels also last longer than often assumed. NREL’s life-cycle analysis models US utility-scale PV with a 30-year operating life13 and 0.7% annual degradation. Performance warranties commonly guarantee about 80–85% of output at 25–30 years. Investors therefore have a longer earning window after payback than a 15–25-year lifespan would suggest.
For a quick comparison, the payback period of investment in housing is also approximately 10 years, but the lifespan of a housing property varies from 50 to 100 years, depending on the property quality, location, maintenance, etc. Even in the worst case, the period of benefit after payback is much longer than for a solar installation.
For this reason, renewable energy suits investors with deep pockets and long horizons. Large infrastructure funds and the biggest private equity firms are best placed to carry the upfront costs and the policy risk, even with all the incentives and benefits.
Private Equity Investment in the Renewable Energy Sector
Private equity interest in renewable energy has not faded. Instead, it has concentrated in the largest platforms. Major 2025 fund closes included EQT Infrastructure VI (€21.5bn), Copenhagen Infrastructure Partners Fund V (€13bn) and a $20bn energy-focused Ardian fund. In Europe, private capital is taking on an expanding role in infrastructure14. Fund managers also report strong demand for energy transition and data centre strategies15 going into 2026.
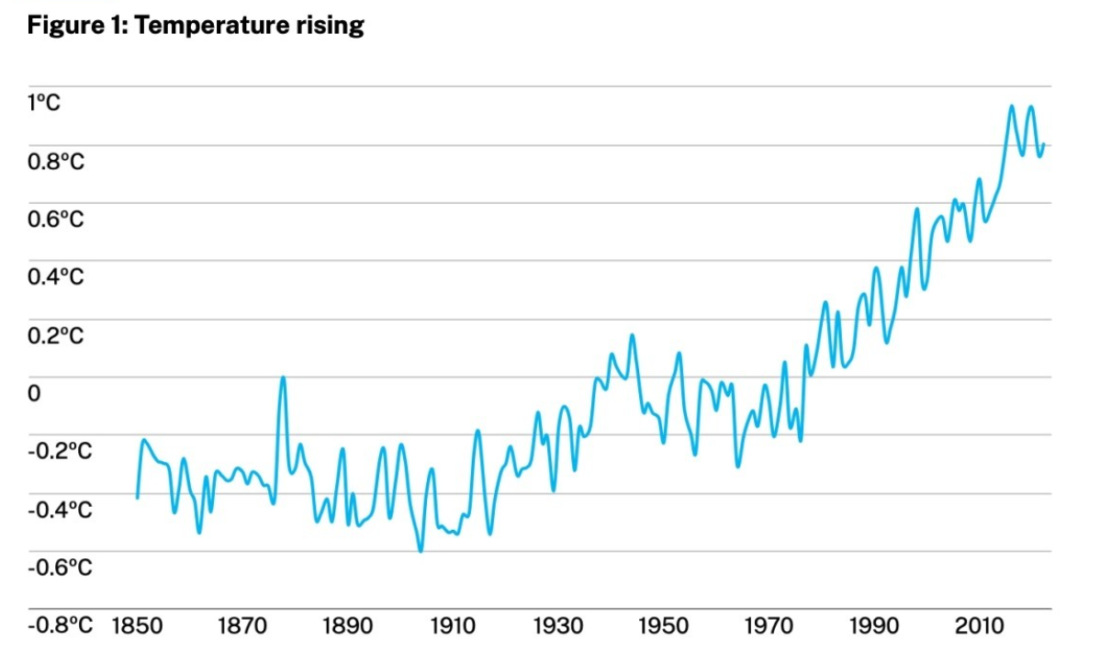
Climate change keeps governments under pressure to support alternative energy. The WMO’s State of the Global Climate 202416 confirms that 2024 was the warmest year on record, at 1.55 ± 0.13°C above the 1850–1900 pre-industrial average. It was likely the first calendar year above 1.5°C.
Long-term warming, averaged over decades, is about 1.3°C, so the Paris goal has not yet been breached. Still, the ten years from 2015 to 2024 were the ten warmest on record. To meet the goals of the zero-emission strategy, clean energy use has to grow17 as shown in the graph below.
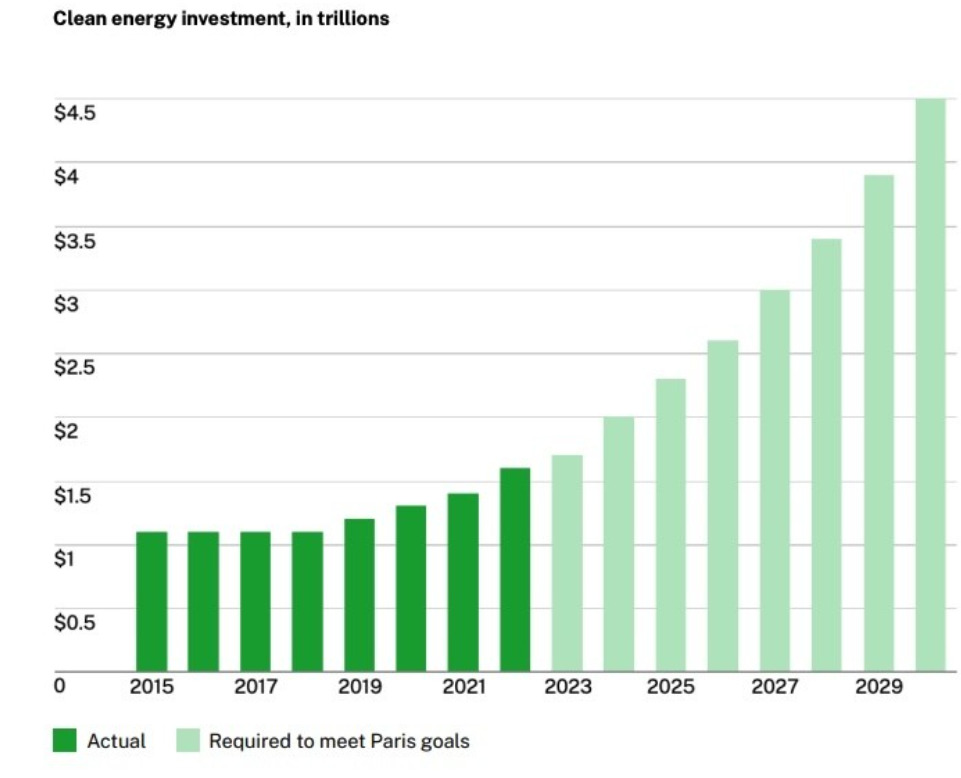
That growth is unevenly spread. China is now the largest energy transition market. Africa, by contrast, attracts only about 2% of global clean energy investment despite having about 20% of the world’s population, according to IEA data summarised by IIGCC18.
Many expected 2023 to be a turning point for renewables, and deployment did accelerate. The world added 582 GW of renewable capacity in 202411. IRENA found that 91% of new utility-scale renewable capacity3 commissioned that year produced power more cheaply than the cheapest new fossil fuel option. Renewables also helped avoid $467bn in fossil fuel costs in 2024. Private equity plays an important role in financing this build-out.
Government incentives continue to shape where that capital goes:
- Tax credits. In the US, the Inflation Reduction Act’s tech-neutral 45Y production and 48E investment credits lower project costs for sponsors. However, the One Big Beautiful Bill Act, signed on 4 July 202519, cut them short for wind and solar. The 4 July 2026 begin-construction deadline has now passed, so new wind and solar projects must be placed in service by 31 December 2027 to qualify. Projects that started construction in time generally have four years to be placed in service. Energy storage keeps the full credit for construction starting through 2033, then 75% in 2034 and 50% in 2035. The 45X manufacturing credit ends for wind components sold after 2027. Treasury’s Notice 2025-42 narrowed the begin-construction rules, but a court later vacated it, so the physical work test and the 5% safe harbor are available for now. Check the latest Treasury guidance before relying on either.
- Renewable portfolio standards according to which a part of sourced energy shall be supplied from renewable sources.
- Long-term price support for renewable electricity, either through fixed feed-in tariffs or through contracts awarded in competitive auctions.
- Bans and targets for fossil fuels also drive the transition to renewable energy.
The share of renewable electricity in the total amount of electricity consumed in the USA is increasing20.
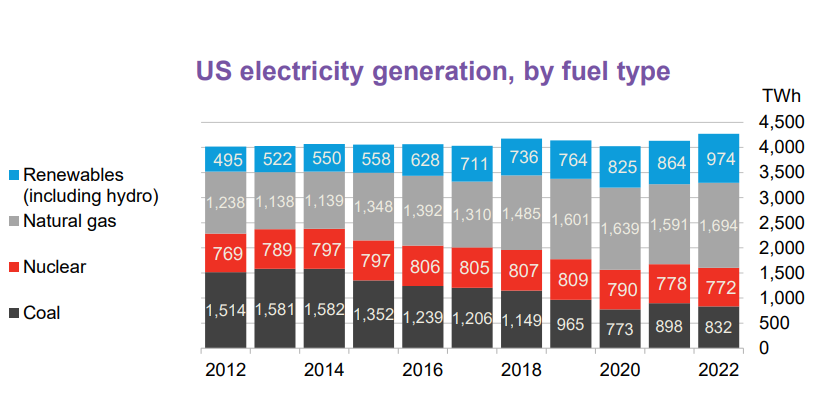
Among all the sources of renewable energy, wind and solar prevail. According to the IEA7, solar PV and wind accounted for 98% of the growth in power generation investment over the past decade.
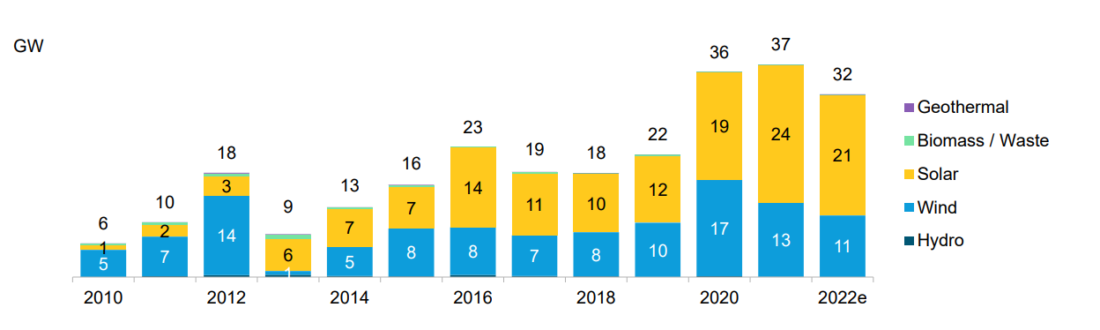
Thus, these sectors attract the most attention from private equity investors. Indeed, solar and wind energy is unlimited, and as soon as the technology develops enough to replace coal and gas installations, the sector will become a goldmine.
How to Build a Private Equity Investment Platform with LenderKit
If you are thinking about benefiting from investment opportunities in renewable energy, you can launch a private equity investment platform with a LenderKit white-label private equity software.
With LenderKit, you can reduce paperwork and automate all investment operations from user onboarding to campaign running and transaction management. The software comes with the regulations-friendly features that help you facilitate compliance with the local regulatory requirements in the USA and EMEA region.
If you want to see how LenderKit investment software works, feel free to schedule a live demo session, or get in touch with us to discuss details and pick the optimal set for you.
Article sources:
- Q2 2024 update: renewable energy related private equity activity in the power industry
- BloombergNEF Finds Global Energy Transition Investment Reached Record $2.3 Trillion in 2025, Up 8% from 2024 | BloombergNEF
- Azure WAF
- Global average solar LCOE stood at $0.043/kWh in 2024, says IRENA - pv magazine Global
- IRENA Report: onshore and offshore wind — the most cost-competitive power generation globally - Baltic Wind
- 2050 long-term strategy - Climate Action - European Commission
- Just a moment...
- Infrastructure Quarterly: Q4 2025
- Just a moment...
- Wind Turbine Cost: Is It Worth The Price In 2026?
- IRENA’s 2024 Renewable Power Generation Costs Report Confirms Renewables Outcompete Fossil Fuels, With Solar PV 41% And Onshore Wind 53% Cheaper Than Lowest-Cost Fossil Alternatives
- Access to this page has been denied
- PDF (https://docs.nrel.gov/docs/fy24osti/87372.pdf)
- Private capital takes on expanding role in European infrastructure
- Infrastructure Outlook 2026: Fundraising Momentum Returns
- State of the Global Climate 2024
- Why 2023 could be pivotal for the future of energy transition | World Economic Forum
- World Energy investment 2025 highlights electricity demand and energy security as new drivers
- The “One Big Beautiful Bill” Act – Navigating the New Energy Landscape | Insights | Sidley Austin LLP
- Just a moment...